
Primary Health Properties stock offers high yield as income focus grows
Published on 09/20/2026 at 21:52 | Editorial responsibility: Rafael Müller, Editor-in-Chief AD HOC NEWS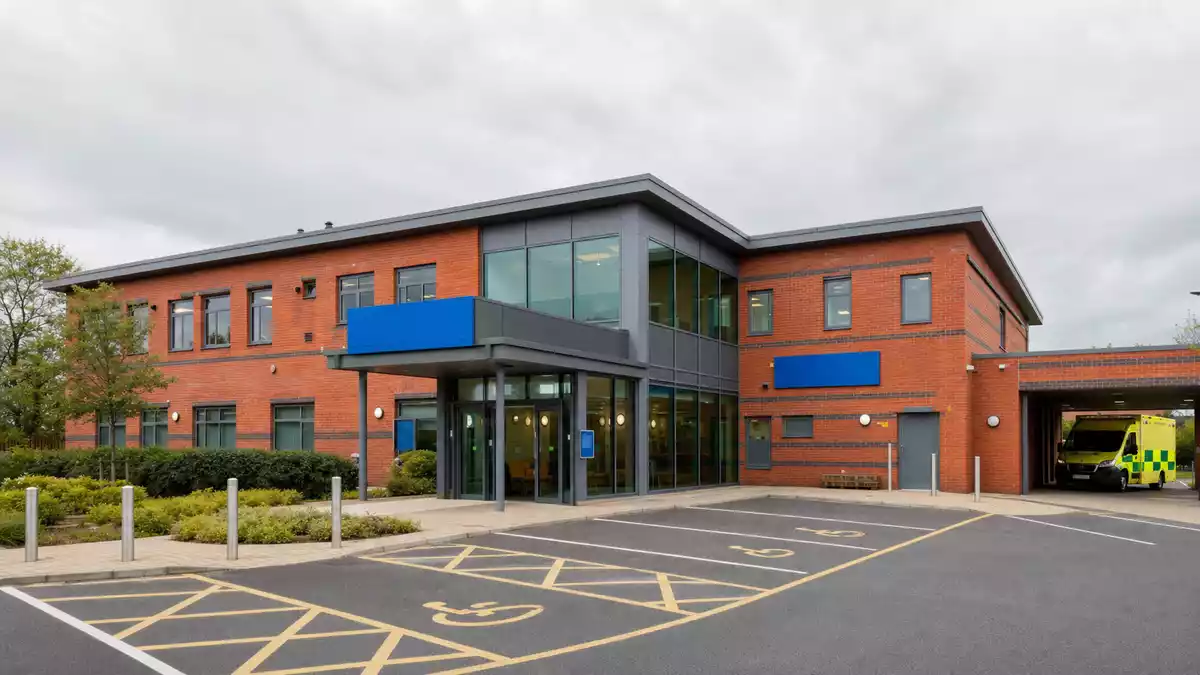
Primary Health Properties stock (ISIN GB00BYRJ5J14) is drawing attention from income-focused investors, with analysts cited on September 20, 2026 expecting a cash dividend of 7.3 pence per share for 2026, which implies a yield of about 7.8 percent at a share price around 93 pence.Twelfth Magpie For investors, the combination of a relatively high yield and a low valuation multiple has become the central theme for Primary Health Properties in September 2026.
Dividend yield and valuation in focus
According to Twelfth Magpie on September 20, 2026, the expected 2026 dividend of 7.3 pence per share on Primary Health Properties translates into a yield of roughly 7.8 percent when measured against a share price of 93 pence, underscoring the REIT's appeal as a passive income vehicle. This forecast payout is modestly higher than the level implied by a 7.9 percent yield that another analysis cites for the stock, again anchored around the same 93 pence share price, which points to a consistently elevated yield profile for the company.Twelfth Magpie
The same comparative piece notes that Primary Health Properties stock is trading on a forward price-to-earnings ratio of about 8.4 as of September 20, 2026, placing it at a discount to many other UK-listed real estate investment trusts and reinforcing the perception that investors are paid a relatively high income for each unit of earnings.Twelfth Magpie In other words, at a share price of 93 pence, the implied earnings base that delivers the 8.4 times forward multiple drives both the income and valuation narrative for the REIT. For income investors comparing options across the UK market, a yield near 7.8 percent combined with a single-digit forward P/E is a notable combination.
Business model and recent financial context
Primary Health Properties focuses on owning and managing purpose-built primary healthcare facilities, typically leased to general practitioner practices and related operators under long-term agreements, which means its cash flows are closely tied to public healthcare spending and lease-cover metrics rather than discretionary consumer demand. This model is generally considered defensive, and the current yield near 7.8 percent as of September 20, 2026 reflects both the rental income stream and the way the market has priced the shares.Twelfth Magpie While the detailed most recent half-year or full-year numbers for the company are not broken out in the latest commentary, the emphasis on the forward dividend and earnings expectations suggests that analysts see the current distribution as supported by forecast rental income and operating cash flow.
In the broader REIT comparison, analysts explicitly highlight Primary Health Properties alongside other income-oriented property vehicles because of its relatively high yield and low valuation multiple, implying that the company has been positioned as a candidate for buying on weakness over the summer of 2026.Twelfth Magpie For investors, this context matters because it frames the current yield and forward P/E not just as static descriptors but as part of a broader view that the shares offer value relative to both income and earnings benchmarks in the UK real estate sector.
Risks behind the high yield
The high implied yield on Primary Health Properties stock also points to underlying risks that the market is pricing in, including higher interest rates and refinancing costs across the real estate sector, which can pressure net income once borrowing expenses are taken into account. Analysts discussing the stock in September 2026 stress that a yield near 7.8 percent is attractive but may also reflect investor caution about long-term funding costs and potential valuation volatility in UK-listed REITs.Twelfth Magpie For shareholders, this means the income stream is not risk-free even though the tenant base is largely anchored in the primary healthcare system.
Another factor highlighted in the comparative REIT analysis is that while Primary Health Properties trades on a low forward P/E of around 8.4, this valuation could compress further if property values or rental growth assumptions are revised downward, or if debt markets remain tight for an extended period.Twelfth Magpie Investors therefore need to weigh the attraction of a 7.8 percent yield against a realistic assessment of interest rate and sector-wide risks that could affect both earnings and dividends over the medium term.
Stock level and investor takeaway
As of September 20, 2026, commentary around Primary Health Properties stock consistently references a share price in the region of 93 pence on its London Stock Exchange primary listing, which serves as the basis for calculating both the approximately 7.8 percent expected yield and the forward P/E of about 8.4.Twelfth Magpie Though intraday price moves are not detailed, the numerical relationship between the 7.3 pence expected dividend and the 93 pence share price frames how much income investors receive relative to each unit of capital deployed.
Primary Health Properties stock snapshot
- Company: Primary Health Properties plc
- ISIN: GB00BYRJ5J14
- Ticker: PHP
- Trading venue: London Stock Exchange
- Price (as of September 20, 2026): 0.93 GBP
- Market capitalization: 0.93 GBP share price with high yield context (as of September 20, 2026)
- Sector / Industry: Real Estate Investment Trusts, Healthcare
- Index membership: FTSE listed UK REIT universe


