Almonty: A Mill at Full Tilt, a Cargo Booked for 2026, and $48 Million of Its Own Stock
Published on 10/27/2026 at 15:11 | Editorial boerse-global.de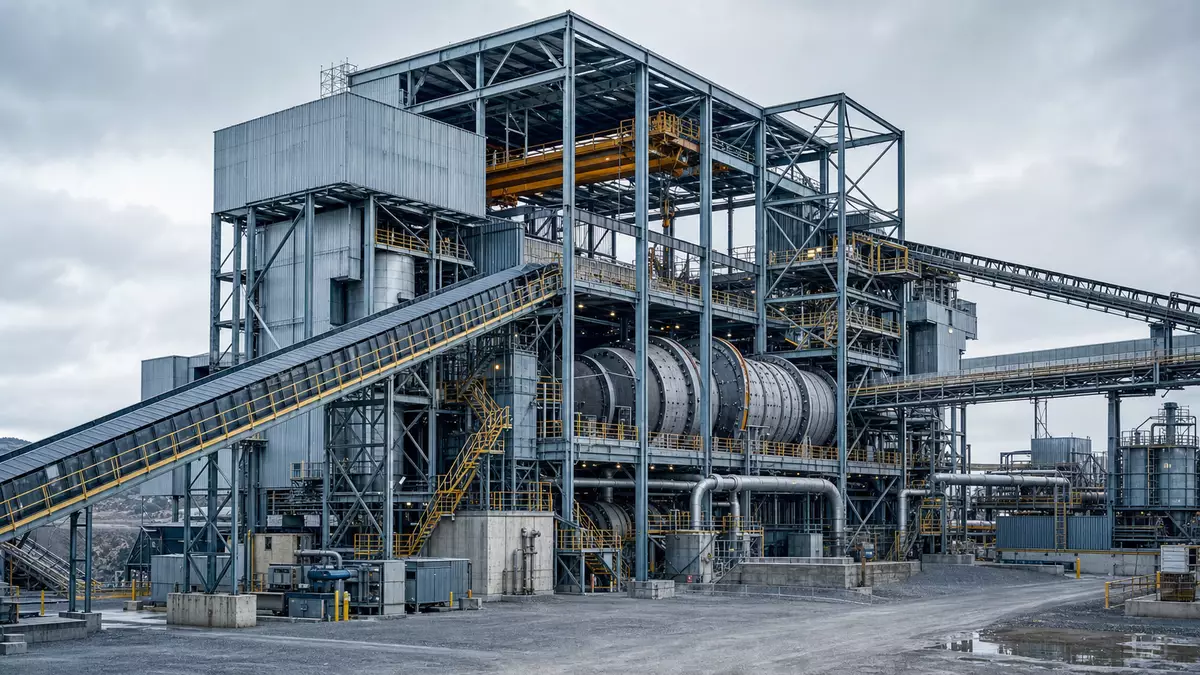
Almonty's story now runs on two tracks that investors would do well not to blur. One is the physical ramp-up at Sangdong, where the processing plant has been hitting its stride. The other is the paper trail of capital decisions — buybacks, listing ambitions, revised analyst timelines — that surrounds it. Progress on the first says nothing definitive about the second, and vice versa.
What the mill is actually doing
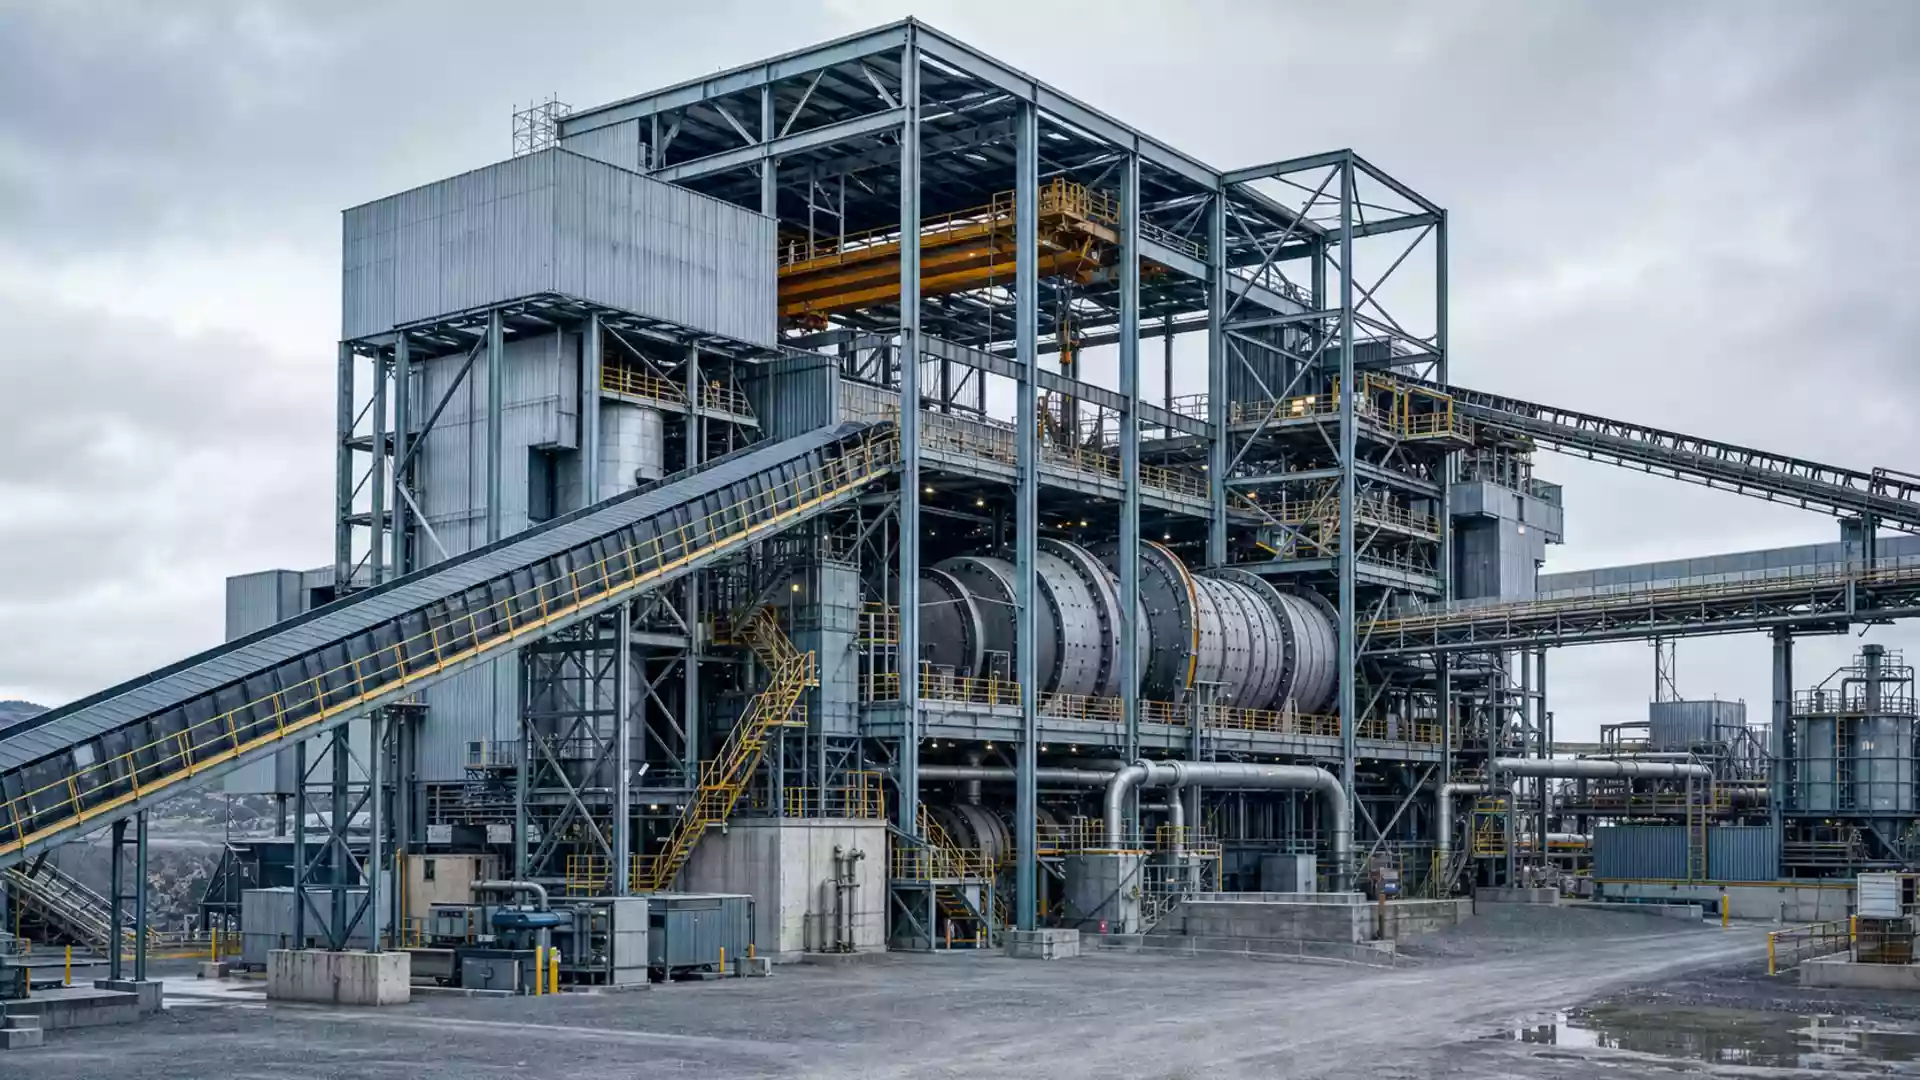
Diamond Equity Research, in a note published roughly a week ago, reported that Sangdong's grinding circuit had reached full throughput. Early in October the mill was running about 16 hours a day. Those two figures describe different things: throughput measures what the plant can process, while daily runtime speaks to how intensively it is being used. Neither should be mistaken for a completed sale.
CEO Lewis Black framed the operational picture in similar terms, saying the grinding circuit was operating at full throughput with recoveries in line with expectations. Processing performance and metal recovery are separate sides of the same coin, and taken together they offer a more meaningful read on the ramp-up than any single headline.
That headline did arrive: Black confirmed that on Saturday the mine shipped its first commercial tungsten consignment in more than 30 years. It is a tangible marker, no question. But a shipment answers a different question than the one about sustained, repeatable production.
Should investors sell immediately? Or is it worth buying Almonty?
A vessel booked is not a vessel sailed
The same Diamond Equity analysis noted that the first ship had been booked for October 24, 2026. A booking is transport preparation, not proof of departure — and even after the scheduled date, the original statement remains, in substance, a reservation. Investors should treat it accordingly.
Timing more broadly has become the pressure point. At the investor day held just over a week ago, Almonty presented revised scheduling expectations for both Sangdong phases. That shift did not go unnoticed on the sell side. On October 20, Stifel cut its price target to US$21 from US$25 while keeping its Buy rating. Brock Cannon tied the adjustment to changed assumptions about the delivery timing of the two expansion stages. The distinction matters: a fundamentally positive view can survive intact even as a more cautious schedule weighs on valuation. Technical headway and rating pressure are not mutually exclusive.
The stock added 2.3% in today's session, though no reliable link to any single news item can be drawn from that move. A day earlier it had climbed 4.6%.
Buybacks, and a Korean listing on the drawing board
Away from the mine, capital allocation deserves its own hearing. Diamond Equity reported buybacks of 2,914,739 shares for approximately US$48 million through the end of September. That is a quantified deployment of capital and should be assessed on its own terms — it documents money spent on the company's own equity, not the pace of deliveries out of Sangdong.
Almonty at a turning point? This analysis reveals what investors need to know now.
Media reports roughly a week ago added another thread: talks about a possible additional Korean listing, with Korean depositary receipts floated as one route. The existing foreign listing is expected to be retained. Here too, modality is everything — discussions about a possible listing are not a completed capital-markets transaction.
The yardstick that matters
The more convincing test for investors is not the count of celebrated firsts. It is whether plant performance, recovery rates and shipping logistics line up consistently. Almonty's disclosures offer concrete evidence of movement in that direction, and it deserves credit as progress. What they do not offer is a free pass to treat the demands of a dependable ramp-up as already met. Commissioned capacity, prepared transport, share repurchases and contemplated exchange plans each stand at their own stage of completion, and none substitutes for another.
Ad
Almonty Stock: New Analysis - 27 October
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.