Deutz Bets on Two Engines of Growth: A Compact New Motor and a Defence Margin Promise
Published on 11/13/2026 at 02:50 | Editorial boerse-global.de
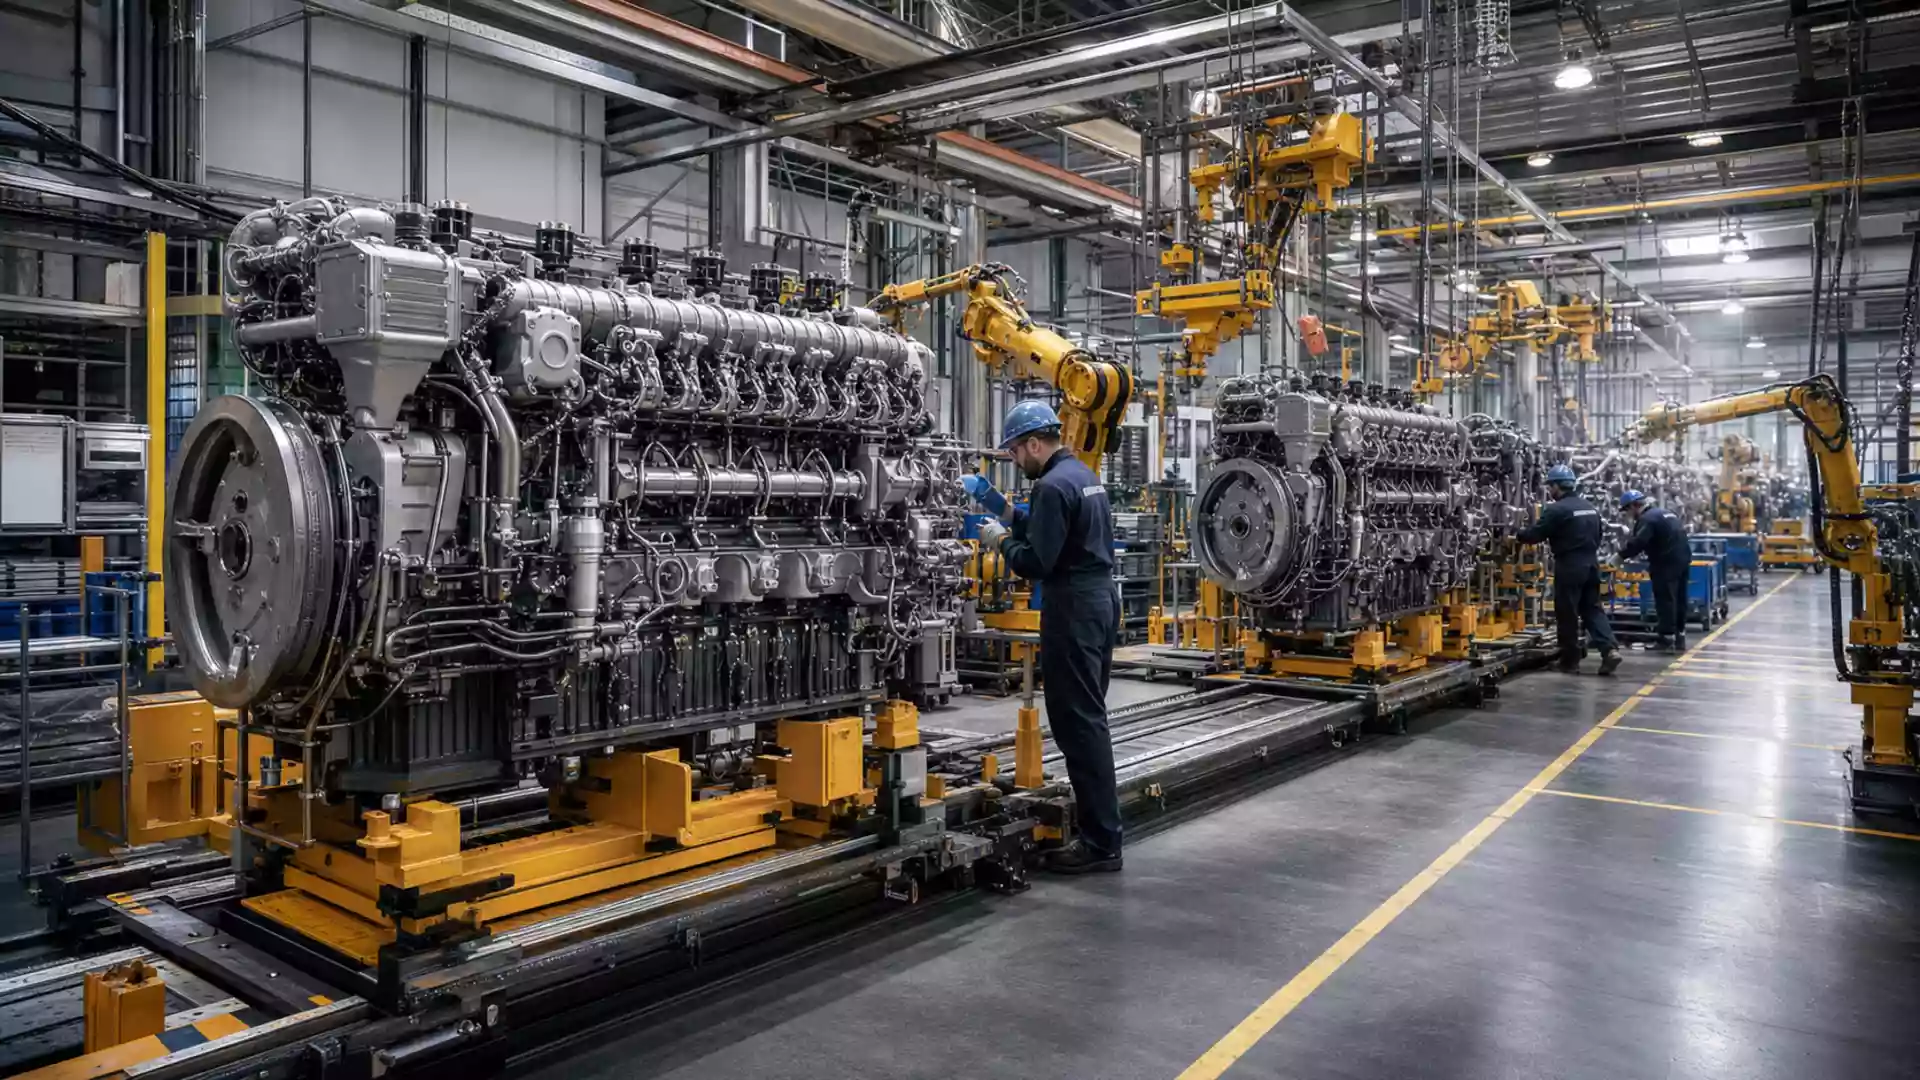
Deutz used Tuesday's EIMA 2026 trade fair to pull the wraps off its TCD 1.6 engine, a new powerplant aimed at compact agricultural and specialty machinery. The launch gives investors a tangible product to weigh against a separate and far larger ambition — the defence-driven growth that Deutsche Bank Research believes can re-rate the stock.
The shares slipped 2.5% on the day, a modest move that says little about either story. What matters more is whether Deutz can convert a broadening product range and a bulging order book into the profitability it has publicly promised.
A product debut, and a parallel wager
The TCD 1.6 targets the small end of the off-highway market, where Deutz already sells into farming and niche applications. It arrives alongside expectations of additional vehicle orders — a Dutch vehicle contract and possible follow-on business for recovery vehicles and the Bundeswehr's wheeled-vehicle programme, according to the research note published Monday.
Those are different kinds of catalysts. One is a finished product; the others are prospective contracts. The breadth itself is the more useful lens, provided the pipeline eventually shows up in revenue rather than remaining a list of talking points.
Should investors sell immediately? Or is it worth buying Deutz?
The numbers already on the table
Deutz reported on 5 November that revenue for the first nine months of 2026 reached EUR 1,669.2 million, with adjusted EBIT of EUR 118.2 million — a 36.0% increase. The adjusted EBIT margin came in at 7.1%.
Orders told an even stronger story. Intake over the same period totalled EUR 1,962.5 million, up 30.4%, giving the growth narrative a firmer foundation than sentiment alone.
Management reaffirmed full-year 2026 revenue guidance of EUR 2.3 billion to EUR 2.5 billion and expects the adjusted EBIT margin at the upper end of its 6.5% to 8.0% range.
Where the real test lies
The headline ambition sits further out. Deutz expects FFG to add more than EUR 1 billion in defence revenue by 2027, paired with an adjusted EBITDA margin above 20%.
That combination — scale plus high profitability — is the yardstick investors should hold management to. Note the distinction between the two measures: the defence target is framed in adjusted EBITDA margin, while the reported improvement refers to adjusted EBIT. Judging progress requires matching each claim to its own metric.
Deutsche Bank Research initiated coverage on Monday with a Buy rating and a EUR 14.50 price target, citing the defence business and anticipated follow-on orders as the growth drivers. The call fits the optimistic case, but its weight depends on contracts actually materialising at the promised margin.
A shareholder bloc with a boardroom agenda
Ownership is the other moving part. Four investor groups connected to FFG reported combined voting rights of roughly 29.9% on Tuesday and are seeking influence over the composition of the supervisory board.
Deutz at a turning point? This analysis reveals what investors need to know now.
That makes governance a second front for shareholders to watch, alongside operational delivery. How much it matters will depend on the steps that follow the disclosure.
What would change the picture
The bear case is straightforward: if the additional defence business arrives smaller or less profitable than advertised, the optimistic scenario loses its footing even while revenue keeps climbing. A permanently positive read on Deutz requires the defence expansion to reinforce, not dilute, the earnings momentum already visible in the nine-month figures.
The next concrete checkpoint is follow-on defence orders of the kind Deutsche Bank anticipates. Until then, the TCD 1.6 and the margin pledge sit on the same question — whether Deutz can turn a wider set of opportunities into profitable business.
Ad
Deutz Stock: New Analysis - 13 November
Fresh Deutz information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.